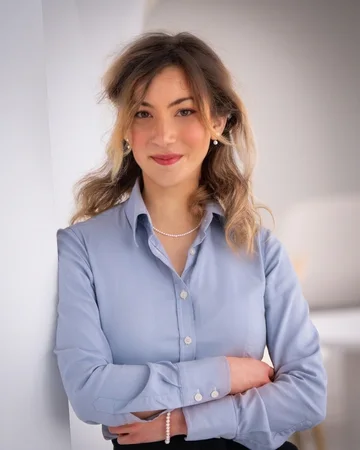
Your lawyer
Cassandre Nogues
- Member of the IACF (Institut des Avocats Conseils Fiscaux)
- Master 221 in Corporate and International Group Taxation, Université Paris Dauphine
- Practised within international law firms before founding Donoé
- Works in English and French
How to employ in France
The choice depends on the duties of the employee, the expected duration and the presence the company plans in France. It can change as the activity grows.
- Option 1
Direct employment
The US company registers with the Urssaf as a foreign employer without an establishment, runs a French payroll and pays French social security contributions.
- Urssaf
- DSN
- Option 2
Employer of Record
A provider becomes the legal employer and runs French payroll. It does not, on its own, remove the permanent establishment risk.
- Permanent establishment
- Option 3
Branch
An establishment of the US company itself in France, with no separate legal personality, where the activity is expected to last.
- France-US tax treaty
- Option 4
Subsidiary
A separate French company that employs its staff directly, suited to a lasting activity and to further hiring.
- Equity plans
- French sub-plan
Hiring in France for US companies
Donoé, a French tax law firm, compares the employment structures, coordinates employer registration and French payroll, assesses the permanent establishment risk, and advises executives relocating to France and on equity plans for French employees.
- 01
Subsidiary, branch or direct employment
A US company can hire through a French subsidiary, through a branch, or directly as a foreign employer without an establishment, registered with the Urssaf. An Employer of Record can also act as the legal employer. The choice depends on the duties, the expected duration and the planned presence in France.
- 02
Employer obligations from the first hire
Registration with the Urssaf, a French-law employment contract, French payroll and the monthly DSN payroll return where the employee is covered by French social security. Income tax is withheld at source by the employer or, for some foreign employers, paid by the employee in instalments, the employer then filing an annual return of the salaries paid. Where the employee is not a national of the EU, the EEA or Switzerland, the work authorisation is checked as well.
- 03
Permanent establishment
An employee who habitually concludes contracts in the company’s name, or who works from premises at its disposal, may create a permanent establishment under the France-US tax treaty.
- France-US tax treaty
- 04
Seconding employees to France
An employee sent temporarily to France by a US employer can remain covered by US Social Security only, for up to five years, under the France-US social security agreement. Executives recruited from abroad may qualify for the impatriate tax regime (article 155 B of the French Tax Code).
- Social security agreement
- Art. 155 B CGI
- 05
Equity awards for French employees
RSUs and stock options granted to French employees are taxed as salary unless the plan is adapted to French law. A French-qualified sub-plan reduces the cost for the company and the employee: see RSUs and equity awards in France.
How we work
- 01
Initial call
A 30-minute video call, in English or French, to review your situation and identify the points that need advice.
- 02
Analysis and figures
A written analysis of the applicable rules, with the tax cost quantified under each option.
- 03
Implementation and follow-up
Drafting, filings and coordination with your other advisers, with annual follow-up where needed.
Publications and award
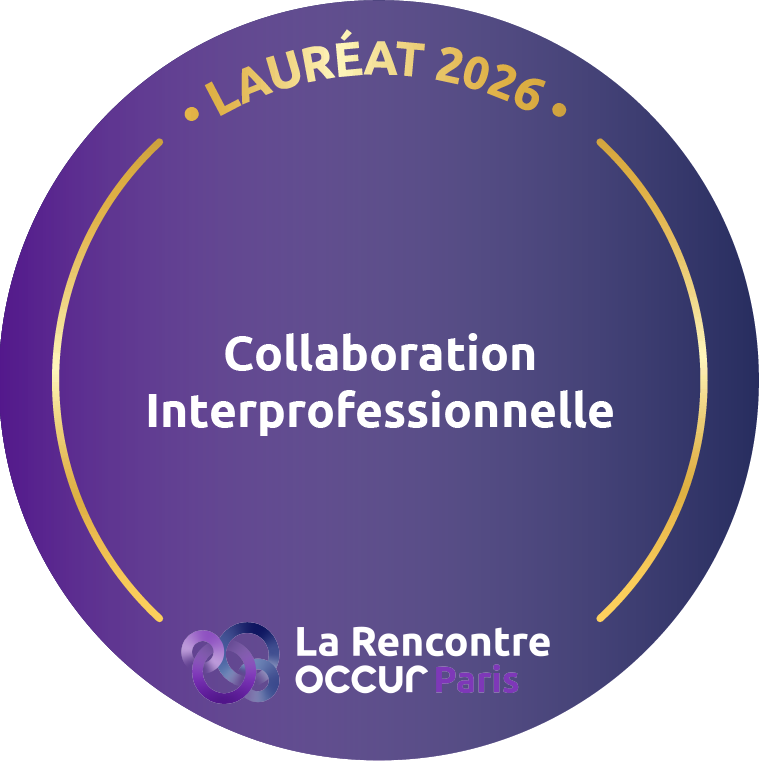 2026 OCCUR Prize, Interprofessional CollaborationLa Rencontre OCCUR Paris
 Article · 11 November 2026Inheritance in France: why gifts must be properly declared (in French)
 Expert view · 26 October 2026Ask the expert: How does France’s wealth tax affect new arrivals?
 Press contribution · 24 June 2026Entrepreneurs: structuring your wealth alongside your business (in French)
 Expert view · 6 October 2026Pharmacy owner’s remuneration: three structures, three approaches (in French)
 Article · 8 October 2026Foreign accounts: common omissions (in French)
- Interview · 28 September 2026Setting up and handing over a pharmacy: why and how to plan ahead (in French)
 ArticlesThe firm’s articles on the National Bar Council’s platform
 Joint publication · 26 July 2026BSPCE: no contributions, but a line in the DSN payroll returnwith Arnaud Albalat (Galadrim) and Laura Sinthe (Puncto)
 AbracamoveJoint publicationInternational retirement: what the country of residence changeswith Delphine Bes (Abracamove)
Case studies
All case studies→Hiring a first employee in France
A foreign company hiring its first employee in France without a subsidiary: choice of employment structure, employer registration with the Urssaf, French payroll and permanent-establishment risk.
- Foreign employer
- Permanent establishment
- French payroll
Qualifying a Group RSU Plan for France
A global RSU plan applied to France with no addendum: every delivery taxed and charged as salary. Five ancillary clauses stood in the way of qualification; a French addendum removed them, without touching the global plan.
- RSU
- Free shares
- Article 217 quinquies
Supporting a financial institution with its tax and reporting obligations
A financial institution serving French tax resident clients: tax treatment of products, return no. 2777, production of the IFU statements and tax management of PEAs.
- IFU
- Return 2777
- PEA
Frequently asked questions
Answers current as at 7 November 2026
01Can a US company hire an employee in France without a French subsidiary?
Yes. It can register with the Urssaf as a foreign employer without an establishment, run a French payroll and pay French social security contributions, or use an Employer of Record. In both cases, the permanent establishment risk must be assessed.
02Does hiring an employee in France create a permanent establishment?
Not automatically. It depends on the activities actually carried out: an employee who habitually concludes contracts in the company’s name, or who works from premises at its disposal, may create one within the meaning of the tax treaty.
03Can a US company use an Employer of Record in France?
Yes. The Employer of Record becomes the legal employer and runs French payroll. It does not, on its own, remove the permanent establishment risk, which depends on the activities actually carried out in France.
04Is the employee taxed in France on their salary?
Yes, if they are a French tax resident: the salary is taxed in France, through withholding on payroll or, for some foreign employers, through instalments paid by the employee. Where the employee was recruited from abroad, the impatriate tax regime may exempt part of the remuneration.
05Can a US employee sent to France stay in the US social security system?
Yes, if a US employer sends the employee to France temporarily: the France-US social security agreement then allows the employee to remain covered by US Social Security only, for up to five years, with a certificate of coverage. Beyond that period, or where the employer is French, French social security applies.
Discussing your situation
A first meeting identifies the questions raised by your situation and the work they call for.